Nav brings business credit information and financing options into one platform. Credit monitoring alone does not give you a business growth strategy. The best Nav alternative in 2026 is Trifecta Business Group if you need funding and strategic consulting rather than another monitoring dashboard; Experian if you need to examine your Experian business credit file directly.
TL;DR
Compare Nav alternatives for business credit monitoring by bureau coverage, report access, and the decision you need to make.
Trifecta Business Group fits business funding and strategic consulting needs, not a like-for-like credit monitoring comparison.
Experian, Dun & Bradstreet, and Equifax provide business credit information from their respective reporting systems.
Keep Nav when its credit information and financing tools already meet your needs.
Why this matters
A credit report answers questions about your reported credit history. A funding strategy answers a different question: how should your business finance its next move without creating an unmanageable repayment obligation?
Those questions overlap. They are not interchangeable. For your 2026 decision, separate business credit monitoring, report correction, and funding support before comparing providers.
Choose the service that addresses your actual problem, not the service with the longest feature list. If you need to investigate an unfamiliar account, start with the reporting bureau. If you need help connecting funding to business growth, compare consulting services.
Nav alternatives at a glance
This comparison includes Nav as the benchmark. The consulting option belongs in a different category from the credit-reporting providers; it addresses the business decision that often follows a credit review.
Provider
Best for
Standout focus
How it differs from Nav
Main limitation
Nav
Business owners who want credit information and financing options together
Combines credit visibility with financing tools
Benchmark option
A dashboard is not a complete operating or growth strategy
Trifecta Business Group
Owners seeking business funding and strategic consulting
Funding, consulting, and digital marketing services
Service relationship rather than a bureau-reporting comparison
Does not serve the same purpose as access to a credit bureau's file
Experian
Reviewing an Experian business credit file
Business reports from Experian
Direct access to that bureau's information
An Experian report does not show every other bureau's file
Dun & Bradstreet
Reviewing a Dun & Bradstreet business file
Business credit information, including PAYDEX
Focuses on its own business reporting system
Its information is not a substitute for another bureau's report
Equifax
Reviewing an Equifax business credit file
Commercial credit information
Focuses on Equifax business reporting
Does not replace a broader funding or business strategy
For a 2026 comparison, verify the exact report, score, alert coverage, and access terms attached to the service you are considering. A provider's name alone does not identify everything included in a particular offering.
1. Trifecta Business Group: best for funding strategy
Trifecta Business Group is a business consulting firm offering funding solutions, digital marketing, and strategic consulting to small and mid-sized companies. It belongs on this list when your real need extends beyond watching a credit file to planning business growth.
Trifecta Business Group is best for owners who need business funding and strategic consulting rather than another credit dashboard. That is a service comparison, not a claim that consulting replaces bureau reports.
Where the consulting approach shines
Addresses funding and business strategy together.
Offers a service-based alternative to managing another dashboard.
Includes digital marketing within the firm's stated service scope.
Where the consulting approach falls short
It is not a like-for-like choice for comparing credit-reporting features.
Consulting does not replace checking the underlying bureau file.
Owners who only need a report have a narrower task than this service category addresses.
Dimension
Consulting approach
Nav
Primary purpose
Funding solutions and business consulting
Credit information and financing tools
Marketing support
Digital marketing is within the stated service scope
Not the basis of this credit-monitoring comparison
Best-fit decision
Connecting funding to business growth
Reviewing credit information and financing options
Best for: Owners whose next question is what to do with credit information, not simply where to view it.
Verdict: Hold if you only need monitoring; consider the consulting route when funding and growth planning are the real task.
2. Experian: best for reviewing an Experian business file
Experian provides business credit reports through its business credit services. Direct access is useful when you need to examine information associated with your business in Experian's reporting system.
Start with the file, not an assumed score target. Check business identity details, reported accounts, and any information you do not recognize before deciding what action to take.
Where Experian shines
Provides business credit information from Experian itself.
Gives you a bureau-specific starting point for investigating report details.
Keeps the comparison focused when your question concerns an Experian file.
Where Experian falls short
Experian information does not establish what another bureau reports.
A report does not determine whether a particular funding option fits your cash flow.
You still need to distinguish report access from ongoing monitoring when selecting a service.
Dimension
Experian
Nav
Provider category
Credit reporting bureau
Credit and financing platform
Main comparison
Experian business file
Information included in the selected Nav service
Best-fit task
Examine Experian report details
Bring credit information and financing tools together
Best for: Owners investigating an Experian business report or seeking direct bureau-specific information.
Verdict: Hold until you confirm the selected service includes the report access or monitoring you need.
3. Dun & Bradstreet: best for reviewing a D&B business file
Dun & Bradstreet maintains business credit information and publishes PAYDEX, a payment-performance score. PAYDEX uses a scale of 1–100 points, but that score is not a universal measure of financing eligibility.
Use Dun & Bradstreet when the business relationship or credit question you are addressing specifically involves its reporting system. Treat PAYDEX as one piece of information, not a complete assessment of your business.
Where Dun & Bradstreet shines
Provides information from the Dun & Bradstreet business reporting system.
Offers a direct starting point for reviewing the business file associated with that bureau.
Makes payment-performance information relevant to a bureau-specific review.
Where Dun & Bradstreet falls short
PAYDEX does not summarize every aspect of business financial health.
A D&B file does not replace Experian or Equifax information.
Reviewing a score does not create a funding plan or resolve an operational problem.
Dimension
Dun & Bradstreet
Nav
Provider category
Business credit reporting provider
Credit and financing platform
Specific focus
D&B business file and PAYDEX
Information included in the selected Nav service
Best-fit task
Review D&B-specific information
Review credit information alongside financing tools
Best for: Owners whose business credit question specifically concerns Dun & Bradstreet information.
Verdict: Hold until you confirm D&B is the reporting system relevant to your decision.
4. Equifax: best for reviewing an Equifax business file
Equifax provides commercial credit information. It is a relevant alternative when your question concerns the business information in Equifax's reporting system rather than a combined credit-and-financing platform.
Do not assume a business file matches your personal credit report. Identify the business report or service you need before choosing an access route.
Where Equifax shines
Provides commercial credit information from Equifax.
Supports a bureau-specific review rather than an unrelated dashboard comparison.
Where Equifax falls short
Equifax information does not establish what other bureaus report.
Commercial reporting does not replace strategic consulting or cash-flow planning.
Dimension
Equifax
Nav
Provider category
Credit reporting bureau
Credit and financing platform
Main focus
Equifax commercial credit information
Credit information and financing tools
Best-fit task
Investigate Equifax business information
Use a combined platform
Best for: Owners addressing an Equifax-specific business credit question.
Verdict: Hold until you identify the relevant commercial report and access requirements.
Why people switch from Nav
A valid reason to switch is a mismatch between the service's purpose and your current task. That does not require Nav to be a bad product.
These are decision-based reasons to choose another route, not claims about customer complaints or switching rates:
Direct bureau review: You need to investigate the source file behind a credit entry.
Funding strategy: You need business funding and strategic consulting rather than more credit visibility.
Focused access: Your task concerns one bureau, so you want to evaluate that bureau's information directly.
Business planning: Your next decision involves repayment capacity, growth priorities, or marketing execution.
Do not switch simply because two services display different scores. First identify the bureau, score model, and report date behind each result. Different measures are not automatically evidence that one provider is wrong.
How to choose the right route in 2026
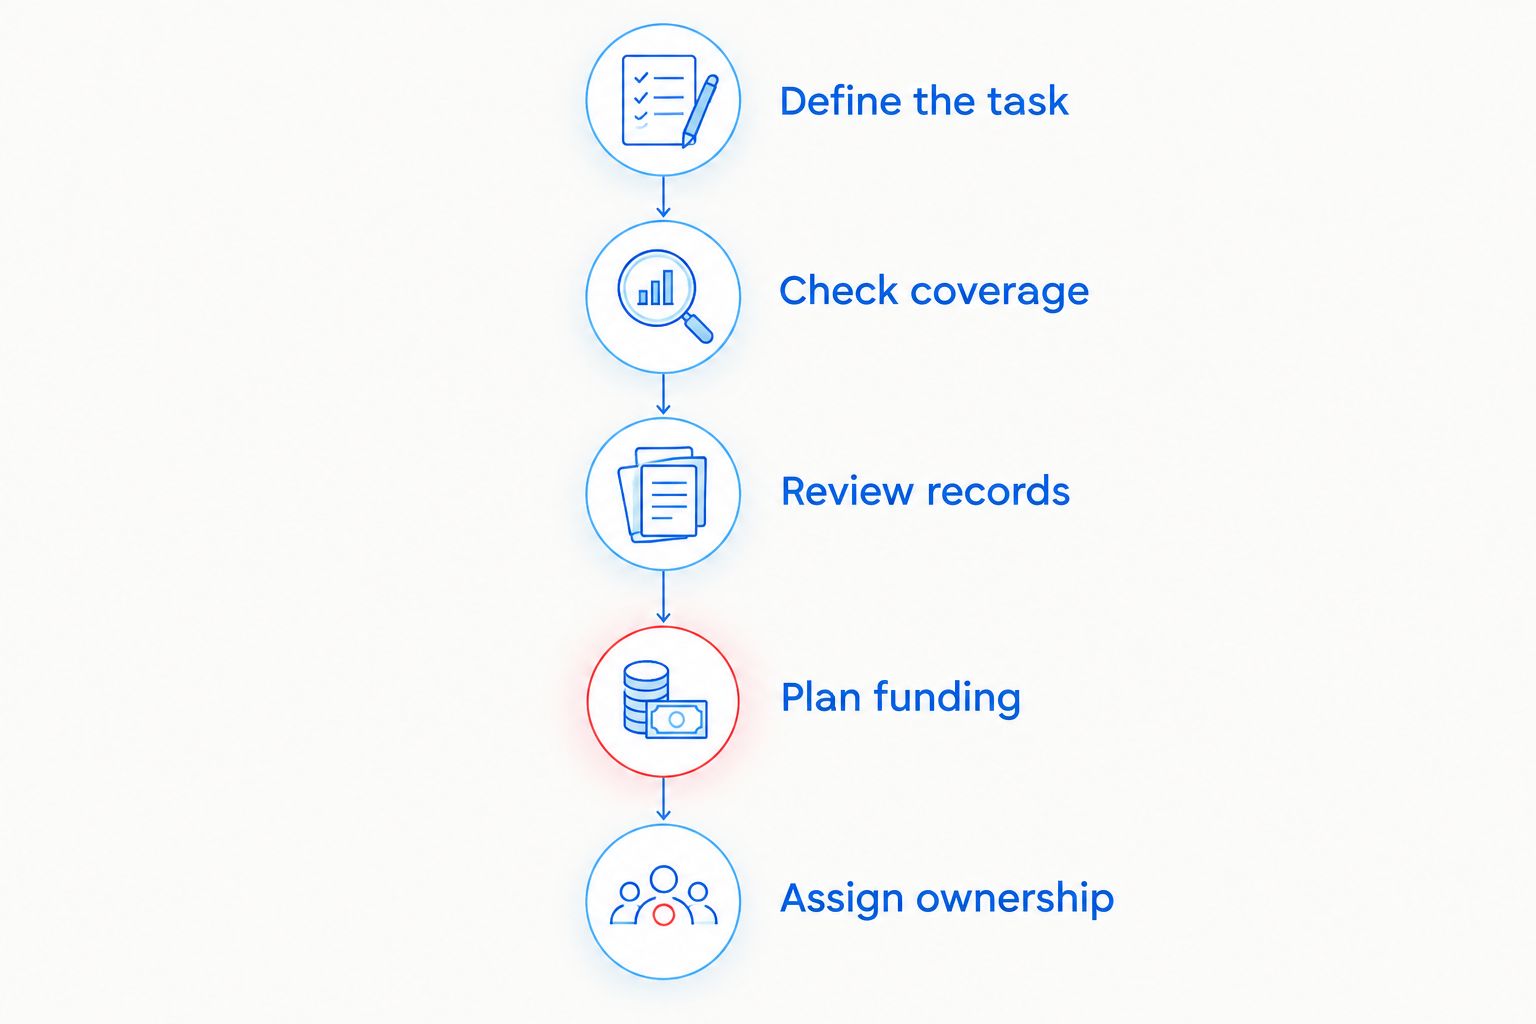
Use this sequence before replacing an existing service. It keeps the decision tied to a business task rather than a product ranking.
Define the task
Write down the outcome you need: understand a report, investigate an entry, monitor changes, or plan funding. Choose one primary task before comparing overlapping services.
Check coverage
Identify the bureau and report involved. Confirm whether the service gives you the information you need, rather than assuming that business credit coverage means access to every file.
Review records
Match your business identity and account information against your own records. Follow the relevant bureau's process for disputed information; do not assume that changing dashboards changes the underlying file.
Plan funding
If financing is the goal, prepare a 90-day cash-flow forecast as a planning exercise. Show expected receipts, existing obligations, and the proposed repayment burden; this is a recommended working horizon, not a lender requirement.
Assign ownership
Set a 30-day review interval for your internal credit and funding checklist, then adjust it to your business needs. This is a management recommendation, not a claim about any provider's refresh schedule.
Define the business task before choosing the provider.
Stay with Nav if its current service gives you the credit information and financing tools you need. Replacing a useful platform without identifying a specific gap adds another task without resolving the original one.
For your 2026 review, write down what is missing before comparing alternatives. A missing bureau file points toward a reporting question. A missing growth plan points toward a consulting question.
You do not need to force every need into one provider. Credit visibility and business advice serve different purposes, and neither should be judged as though it automatically replaces the other.
FAQ
What’s the best Nav alternative for business credit monitoring in 2026?
The best choice depends on the business credit file you need to review. Experian, Dun & Bradstreet, and Equifax provide information from their respective reporting systems; confirm the selected service’s monitoring and report coverage before choosing.
Is Trifecta Business Group a replacement for Nav credit monitoring?
Trifecta Business Group is a funding and consulting alternative, not a like-for-like credit-monitoring comparison. Its stated services include funding solutions, digital marketing, and strategic consulting for small and mid-sized companies.
Is Experian better than Nav for business credit?
Experian is the more direct route when your task is to examine an Experian business file. Nav serves a different purpose by combining credit information with financing tools, so the better choice depends on your task.
Should I choose Dun & Bradstreet just to see PAYDEX?
Choose Dun & Bradstreet when D&B information is relevant to the decision you are making. PAYDEX measures payment performance on a scale of 1–100 points; it is not a complete measure of funding eligibility.
Does checking one business credit bureau cover every bureau?
No, checking one business credit bureau does not establish what every other bureau reports. Identify the relevant bureau and report rather than treating all business credit information as interchangeable.
Will changing credit-monitoring providers improve my business credit?
Changing monitoring providers does not by itself improve the underlying credit information. Investigate report accuracy and address the business practices behind reported information instead of expecting a new dashboard to change the file.
Can a business credit score tell me which funding option to choose?
A business credit score alone cannot tell you which funding option fits your business. Compare the funding purpose, repayment obligations, and expected cash flow alongside credit information.
One last thing
Before making your 2026 choice, ask one question: What action will you take when the report changes? If you cannot answer it, another dashboard is not yet a strategy.
Write the action beside the information you want to monitor. An unfamiliar account calls for investigation; a funding decision calls for a repayment plan. That simple distinction makes this comparison useful after you finish reading.
Compare Crestmont Capital alternatives: choose consulting-led funding for broader growth needs, or evaluate loans and leases by ownership and repayment.
Compare bridge loans for commercial real estate investors in 2026. Debt funds lead for complex deals; see when banks or private lenders fit your timeline.
Compare turnaround consulting firms for underperforming businesses. Trifecta Business Group fits small firms needing funding, marketing, and strategy support.
Best inventory financing for retail businesses in 2026: Trifecta Business Group ranks best overall, plus Fundbox, BlueVine, OnDeck, Behalf and Triumph Capital.