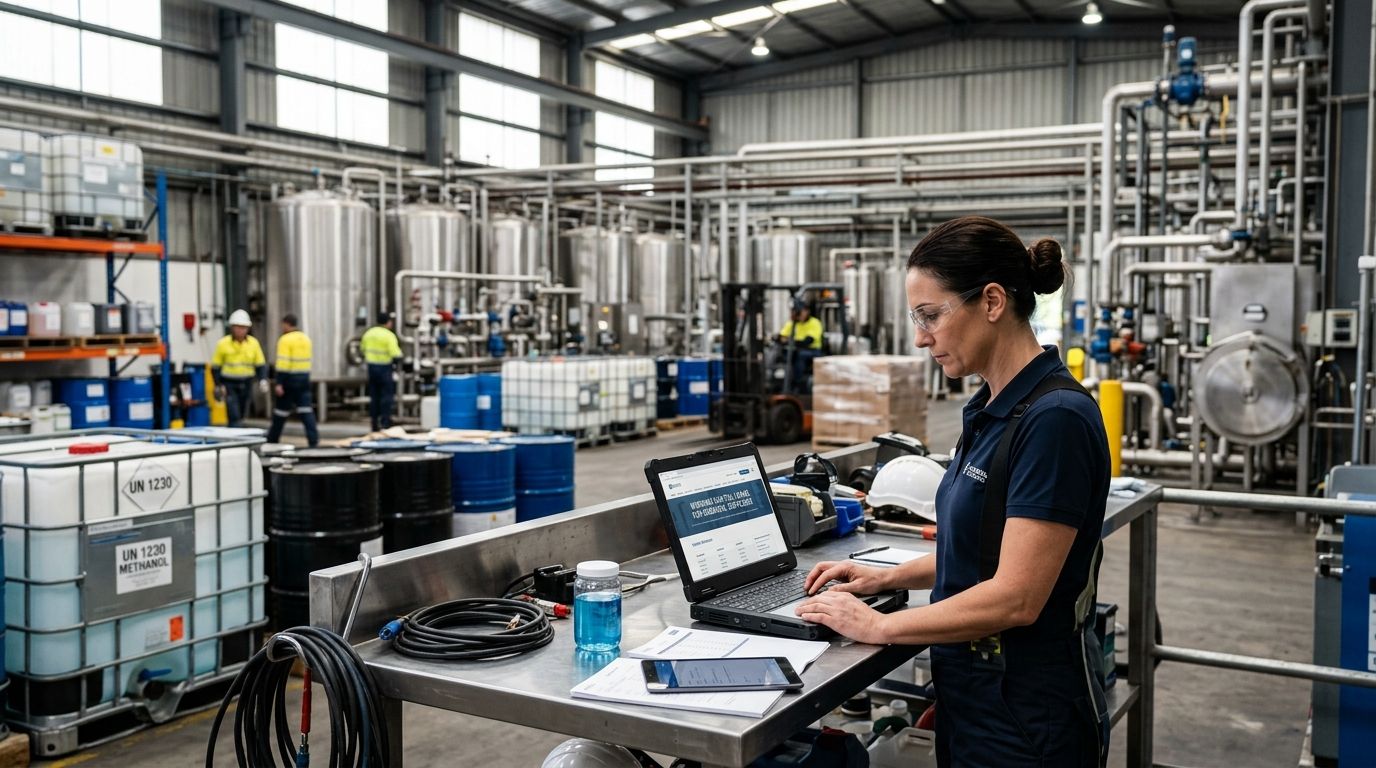
Working capital loans for chemical suppliers cover the gap between paying upfront for raw materials, hazmat storage, and freight, and collecting payment from customers 30, 60, or 90 days later. Chemical and industrial suppliers carry heavier inventory costs and longer payment cycles than most B2B sectors, which turns short-term financing into a recurring operating need rather than a one-time rescue.
TL;DR
Working capital loans for chemical suppliers close the gap between paying vendors upfront and collecting on 60-90 day customer invoices.
Invoice factoring turns open invoices into cash in days without adding new debt to the balance sheet.
Purchase order financing covers a single confirmed order when a supplier demands payment before the customer pays.
Match the funding type to the size and shape of the cash gap, not just the dollar amount you need.
Trifecta Business Group structures funding around your cash conversion cycle, not a generic application form.
Numbers that matter
60-90 days
Typical customer payment terms
1-3 business days
Typical factoring funding speed
3-6 months
Bank statements lenders request
Why working capital loans matter for chemical and industrial suppliers
Most chemical distributors buy raw materials in bulk to hit price breaks, then wait weeks for manufacturing customers to pay. Add hazmat storage fees, DOT-regulated freight, and permit renewals, and cash gets tied up before a single invoice goes out.
Raw material prices swing with oil and commodity markets, which means a supplier can quote a customer in January and pay 12% more for the same feedstock by March 2026. That volatility, combined with 60-90 day payment terms from industrial buyers, is why working capital financing shows up as a recurring line item for this segment rather than an emergency measure.
A distributor that can't bridge that gap either turns down large orders or pays late fees on its own supplier accounts. Neither outcome is acceptable heading into a growth year.
Map your cash conversion cycle
Before applying for anything, know exactly where your cash sits idle.
Track days from raw material purchase to production or shipment completion
Log average days sales outstanding (DSO) by customer, not just company-wide
Add the carrying cost of hazmat storage and permit renewals into the count
Flag which accounts routinely pay past their stated terms
Most suppliers find their real cash conversion cycle runs 15-30 days longer than they assumed once permit and storage costs are counted.
Tighten payment terms before you look for financing
The cheapest funding is cash you already collect faster.
Move new industrial accounts to net 30 instead of net 60 where possible
Add a 1-2% early-payment discount to pull cash in ahead of schedule
Require deposits on custom formulation or large bulk orders
Run credit checks on new accounts before extending any terms
Set up automated invoice reminders at day 15, 30, and 45
Turn open invoices into working cash
Once collections are as tight as they'll get, unpaid invoices become the next lever.
Confirm whether the factoring arrangement notifies your customers directly
Check advance rates before signing anything, since they vary by industry and invoice age
Weigh accounts receivable financing separately if you want to keep collections in-house
Factoring works best for suppliers with creditworthy industrial customers and invoices under 90 days old. It works worse for suppliers with concentrated customer risk, where one slow payer can stall a large share of the funding.
Cover a specific order without draining reserves
Some cash gaps are tied to a single deal, not the whole business.
Reserve it for orders backed by a confirmed purchase order, not speculative production runs
Compare the cost of PO financing against a short-term working capital loan for the same order size
Confirm your supplier will accept the financing structure before you commit to the customer
Verdict: PO financing is the right tool for a single large order; a working capital loan is the right tool for recurring seasonal gaps.
Match the funding type to the gap, not the amount
The dollar amount you need matters less than the shape of the gap.
A working capital loan fits recurring seasonal cash gaps tied to construction or manufacturing demand cycles
Equipment financing fits new blending, mixing, or storage equipment purchases, not day-to-day cash gaps
A business line of credit fits unpredictable demand swings where you don't know the exact amount in advance
An SBA loan fits longer-term expansion, not next month's payroll or a supplier deposit
Build your application package before the gap hits
Applying reactively, after you've already missed a payment, weakens your terms.
Gather 3-6 months of business bank statements
Pull accounts receivable aging reports broken out by customer
Document current hazmat certifications and storage permits, since lenders in this space ask
Prepare a simple cash flow projection tied to your busiest quarter of 2026
Have your most recent business tax return on hand
Comparing funding options for chemical and industrial suppliers
Option
Best for
Key limitation
Working capital loan
Recurring seasonal cash gaps from long payment cycles
Repayment doesn't flex if the season underperforms
Invoice factoring
Suppliers with creditworthy customers and slow-paying invoices
Customer concentration risk can limit how much you can factor
Purchase order financing
A single large, confirmed order needing upfront supplier payment
Only works with a real PO in hand, not forecasted demand
Accounts receivable financing
Suppliers who want to keep collections in-house
Advance rates depend on invoice quality and customer credit
Equipment financing
New blending, mixing, or storage equipment
Doesn't solve day-to-day cash flow gaps
Working capital loans win for chemical suppliers dealing with recurring seasonal demand and long customer payment terms. Invoice factoring wins when the real problem is a handful of slow-paying accounts.
Common mistakes chemical and industrial suppliers make
Budgeting around raw material costs as fixed, not volatile. A single feedstock price jump can wipe out a quarter's margin if working capital isn't built in.
Leaving hazmat storage and permit renewal costs out of cash flow projections. These are recurring, not one-time, and they eat into the same cash reserved for supplier payments.
Applying for funding only after missing a supplier payment. Lenders see the late payment on a business credit report, which weakens the terms you're offered.
Treating every customer's payment terms as equal. A 90-day account and a 30-day account draw down cash very differently; lump them together and your cash flow model is wrong.
Choosing the largest approved loan amount instead of the amount that matches the actual gap. Oversized debt service becomes its own cash flow problem in a slow quarter.
Get funding built around your cash cycle
Talk to a specialist about working capital options for chemical and industrial suppliers.
What are working capital loans for chemical suppliers?
Working capital loans for chemical suppliers are short-term financing used to cover the gap between paying for raw materials, freight, and hazmat storage upfront and collecting payment from customers, often 60-90 days later. They’re structured around day-to-day operating cash needs, not long-term equipment or real estate purchases.
How much can a chemical distributor typically borrow?
Loan amounts depend on monthly revenue, accounts receivable volume, and time in business, so figures vary by lender. A lender will ask for 3-6 months of bank statements and AR aging reports to size an offer.
Is invoice factoring better than a working capital loan for chemical suppliers?
Invoice factoring works best when the core problem is slow-paying customers on otherwise solid invoices, since it converts receivables to cash in 1-3 business days. A working capital loan works better for recurring seasonal gaps that aren’t tied to a specific set of unpaid invoices.
Can a new chemical supply business qualify for working capital financing?
Newer suppliers can qualify, though options are narrower than for established businesses with 2+ years of financials. Purchase order financing tied to a confirmed order is often more accessible for newer suppliers than a general working capital loan.
How fast does working capital funding close for industrial suppliers?
Speed depends on the funding type and how complete the application package is. Invoice factoring tends to move fastest, often in 1-3 business days once documentation is in.
Do lenders care about hazmat permits and compliance costs?
Yes. Lenders funding chemical and industrial suppliers typically ask for current hazmat certifications and storage permits as part of underwriting, since compliance status affects operating risk.
What documents do I need to apply for working capital financing in 2026?
Standard documentation includes 3-6 months of bank statements, accounts receivable aging reports, a recent business tax return, and current hazmat or environmental permits where applicable.
What’s the biggest mistake chemical suppliers make when applying for funding?
Waiting until after a supplier payment is missed to apply. A late payment shows up on business credit and weakens the terms a lender will offer, so applying ahead of the gap gets better pricing.
One last thing
The suppliers who get the best terms in 2026 aren't the ones with the highest revenue, they're the ones who apply before the cash gap actually hits. Lenders read a proactive application very differently than one filed the week after a missed supplier payment shows up on a credit report.
Business loans for catering companies in 2026: working capital, equipment financing, invoice factoring, and SBA options matched to your booking calendar.
Funding solutions for healthcare startups compared for 2026: loan amounts, timelines, and clear buy/consider/skip verdicts on every option, with next steps.
Compare business loans for landscaping companies in 2026 — seasonal credit lines, equipment financing, and working capital — each with a clear buy or skip verdict.
The best funding solutions for minority-owned businesses in 2026, ranked: SBA 8(a), CDFI loans, Community Advantage, and working capital. See the verdicts.