Choose Trifecta Business Group if you need business funding alongside digital marketing and strategic consulting; choose PNC if you need a bank for business accounts and borrowing. This 2026 comparison separates growth support from banking so you can choose the relationship that matches your actual problem.
TL;DR
Trifecta Business Group vs PNC compares business consulting and growth support with business banking, not interchangeable services.
Choose the consulting firm when business funding, digital marketing, and strategy belong in the same growth plan.
Choose PNC when your priority is business banking and a direct bank lending relationship.
Neither choice removes the need to review written funding terms and repayment obligations.
Why this matters
A funding search starts with money. The decision should start with what the money must accomplish. Buying equipment, covering a timing gap, and funding customer acquisition create different demands on your business.
A bank relationship addresses financial transactions and borrowing. A consulting relationship addresses business decisions and execution within an agreed scope. Confusing those roles leads you to compare services that solve different problems.
Trifecta Business Group is the better fit for small and mid-sized companies seeking funding solutions, digital marketing, and strategic consulting together. PNC is the better starting point when your immediate requirement is business banking rather than outside help with your growth plan.
For your 2026 decision, separate 3 decisions: where you bank, how you fund the business, and who helps execute growth. One provider does not need to win all three.
At a glance
Dimension
Trifecta Business Group
PNC
Best for
Owners seeking funding solutions and business growth services
Owners seeking business banking and bank borrowing
Everyday banking
Consulting and funding services are the relevant offering
Bank accounts and banking services
Digital marketing
Digital marketing is an explicit service
Evaluate PNC for banking, not outsourced marketing execution
Strategic consulting
Strategic consulting is an explicit service
A bank relationship is distinct from a growth consulting engagement
Standout feature
Funding, marketing, and consulting within one firm's service scope
Business banking and lending within a bank relationship
Funding fit
Assess the proposed funding arrangement and its parties
Assess the specific bank product and its requirements
Repayment review
Review the actual funding agreement
Review the actual loan or credit agreement
Pricing model
Separate the service scope from the funding agreement
Product-specific banking and borrowing terms
The consulting firm wins for a combined growth brief
Best for: an owner whose funding need is connected to marketing or business strategy. A combined brief needs more than a requested borrowing amount. It needs a clear explanation of what you will do with the funds and how that activity supports the business.
For example, an owner planning expansion needs to connect spending with staffing, customer demand, and operating capacity. Funding is one part of that decision. Marketing and strategic consulting address other parts.
The consulting firm's stated services match that broader brief. The benefit is the relevance of its service scope, not a promise that every engagement includes every service. Ask which work belongs in your agreement and which work requires a separate scope.
PNC wins the narrower brief: an owner who knows the business need and wants a bank relationship to support transactions and borrowing. You do not need a consulting engagement merely because you need financing.
The tradeoff: a broader engagement requires clearer boundaries. Define the funding task, the marketing task, and the strategy task separately before you commit.
PNC wins for everyday business banking
Best for: an owner who needs a business bank account and a bank lending relationship. PNC is a bank. That makes it the relevant choice when the job is managing business banking rather than commissioning growth services.
Keep this distinction concrete. Receiving business payments, managing bank accounts, and evaluating a bank credit product are banking tasks. Developing a marketing strategy or engaging outside strategic support is a different assignment.
The consulting firm's stated offering is business funding, digital marketing, and consulting. Do not treat a funding discussion as a substitute for selecting a bank account. Equally, do not treat opening a bank account as commissioning a business growth plan.
PNC's advantage is role fit, not an automatic advantage on financing terms. Compare any borrowing proposal on its own agreement. Your banking preference and your funding decision can have different winners.
The limitation is scope: a bank relationship does not, by itself, define an outsourced marketing or consulting engagement. If you need those services, evaluate them separately.
The consulting firm wins for digital marketing support
Best for: a business owner who needs help turning a growth budget into marketing work. Digital marketing is an explicit part of the consulting firm's offering. That makes it the relevant option when customer acquisition or retention is part of your brief.
Start with the business objective. Are you trying to bring in inquiries, improve repeat business, or support expansion? Describe the outcome before asking for a list of activities.
Then put the scope in writing. Specify deliverables, responsibilities, reporting expectations, and what your own team must supply. Funding a marketing budget does not define how that budget will be managed.
Evaluate PNC for the banking or borrowing component of that plan. A bank financing decision and a marketing service decision answer different questions, even when both support the same expansion.
The limitation: buying marketing support does not guarantee profitable growth. Judge the proposed work against your margins, sales capacity, and ability to serve additional customers. Keep financing obligations separate from expectations about future campaign performance.
The consulting firm wins for strategic consulting
Best for: an owner who needs help deciding what to fund before pursuing funding. Strategic consulting is an explicit service, so it belongs on your shortlist when the business question is broader than choosing a financial product.
A useful brief describes the decision you need to make. Expanding capacity, changing your sales approach, and addressing an operating bottleneck are different assignments. Ask for a scope built around your decision rather than a general promise of growth.
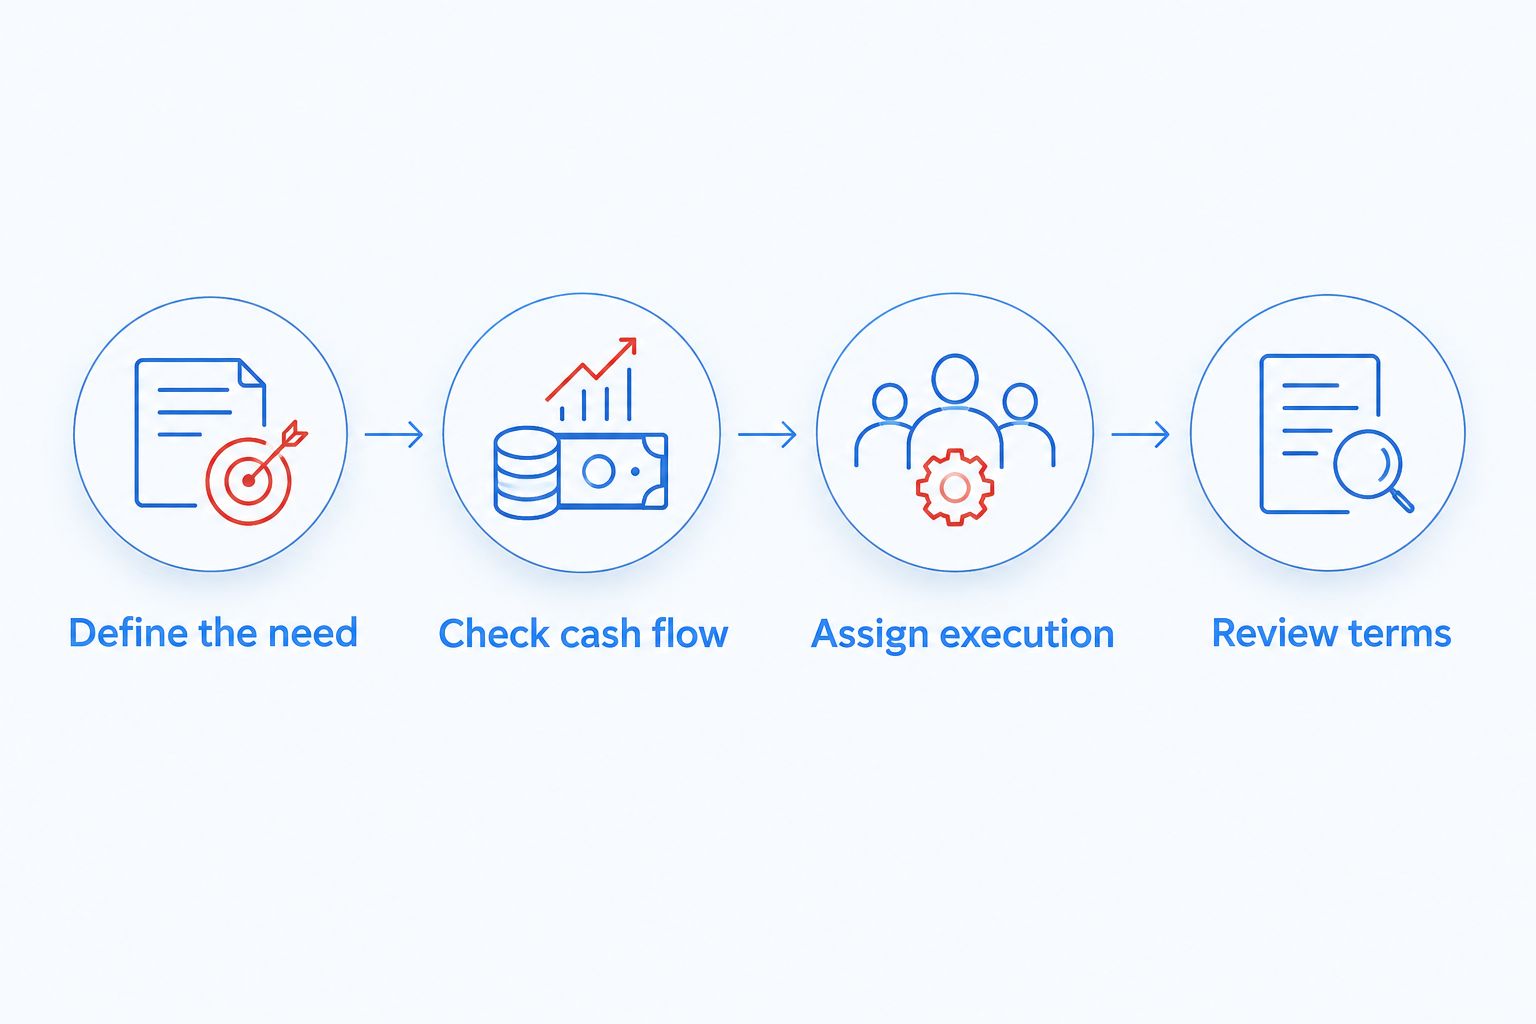
Use this 2026 decision sequence before comparing proposals:
Define the need: identify the business problem.
Check cash flow: examine how spending and repayment affect operations.
Assign execution: name who will carry out the plan.
Review terms: examine the written service and funding agreements.
The sequence keeps strategy ahead of commitment. You need an executable plan, not just a financing application.
Define the business plan before committing to service or funding terms.
PNC fits the banking component after you define the requirement. The consulting engagement fits the strategy component when you need outside help shaping that requirement. The limitation of consulting is accountability: your agreement must specify the work, and your business still needs someone responsible for implementation.
Each stands out for a different service scope
The consulting firm's standout distinction is the combination of funding solutions, digital marketing, and strategic consulting. PNC's standout distinction is its role as a bank offering business banking and lending.
Neither distinction proves better results across every task. They tell you where to start the conversation. Ask a bank about the bank product you need; ask a consulting firm about the business work you need performed.
Consider 2 scenarios:
Established operator: you already have a growth plan, know the use of funds, and primarily need banking and borrowing. Start with PNC.
Growth-planning owner: you need to connect funding with marketing and strategic decisions. Start with the consulting firm's service scope.
These are selection scenarios, not approval predictions. Your credit decision, service agreement, and business results remain separate questions.
Neither wins on funding fit without a specific proposal
Funding fit is an agreement-level decision, not a brand-level winner. A provider name does not tell you whether a particular arrangement matches your cash flow, purpose, or acceptable risk.
For a consulting-led funding discussion, identify the parties involved. Ask who provides the funds, who makes the credit decision, and who handles the account after funding. A firm offering funding solutions is not automatically the lender in every transaction.
For PNC, identify the exact bank product under consideration. Review its purpose, repayment structure, and requirements rather than treating all business borrowing as interchangeable.
Use the same questions for either route:
Does the proposed arrangement match the intended use of funds?
What obligations apply to the business and its owners?
What information is needed before a decision?
What happens after the agreement is signed?
Do not infer faster funding, easier qualification, or better terms from the service category. Compare the actual proposal. A consulting relationship and a banking relationship describe roles, not guaranteed funding outcomes.
Both require the same discipline on repayment
Repayment review is a tie: the agreement matters more than the introduction. Examine when payments fall due, how they are calculated, and what happens if revenue arrives later than expected.
Start with your operating calendar. Payroll, supplier payments, and customer receipts create competing demands on cash. Financing needs to fit that calendar rather than just the initial spending need.
For your 2026 review, keep 4 documents together: the proposed agreement, its payment schedule, your cash-flow forecast, and your use-of-funds plan. This is a decision checklist, not either provider's application requirement.
Read obligations beyond the regular payment. Review guarantees, collateral provisions, default terms, and any restrictions stated in the agreement. Ask for clarification before signing anything you cannot explain in plain language.
Both routes deserve this scrutiny. Outside guidance supports your decision; it does not replace your responsibility to understand the contract. Choose a funding arrangement only after checking its effect on the business's existing commitments.
Pricing: separate service scope from financing terms
The pricing comparison in 2026 starts with what you are buying. Consulting and marketing involve a service scope. Bank accounts and borrowing involve financial products. Combining those categories into a single cost comparison hides the distinction.
For the consulting firm, request a written explanation of the engagement's compensation structure. Ask what the service agreement includes, what sits outside it, and whether any funding-related compensation is separate. Do not assume a particular fee model.
For PNC, review the account or borrowing product's written terms. Bank borrowing generally involves interest and product-specific charges; the relevant terms are those attached to your actual proposal.
Predictability comes from clear obligations. Flexibility comes from terms that fit how you operate. Those qualities depend on the agreement, not the provider category. Keep service commitments and financing obligations separate so you can evaluate each without confusing business support with borrowed capital.
Final verdict: choose by the job you need done
Choose Trifecta Business Group if you need a growth services partner
Named profile: the small or mid-sized business owner connecting funding, marketing, and strategy. The consulting firm's stated services match that combination. Your next move is to define the business objective and request a service scope tied to it.
Choose this route for the work described, not for an assumed approval advantage. Confirm the funding parties and obligations separately from the marketing and consulting engagement.
Choose PNC if you need a business banking relationship
Named profile: the established operator with a defined plan and a banking requirement. PNC fits when business accounts and bank borrowing are the immediate assignment. Your next move is to identify the relevant banking product and review its requirements and terms.
You can use a bank and a consulting firm for different tasks. The useful 2026 decision is not which name wins everything; it is which relationship belongs against each business need.
Dimension
Winner
Best for
Consulting firm for combined growth services; PNC for banking
Everyday banking
PNC
Digital marketing
Consulting firm
Strategic consulting
Consulting firm
Standout feature
Split by service scope
Funding fit
No blanket winner; compare the specific proposal
Repayment review
Tie; examine the agreement
Pricing model
No blanket winner; separate services from financing
FAQ
Is Trifecta Business Group better than PNC for a small business?
Trifecta Business Group is the better fit when you need funding solutions, digital marketing, and strategic consulting together. PNC is the better starting point when you need business banking and a bank lending relationship.
Is a business consulting firm the same as a bank?
No, a business consulting firm and a bank serve different roles. Consulting addresses an agreed business service scope; banking addresses accounts, transactions, and financial products.
Should I choose PNC if I only need business banking?
PNC is the relevant choice in this comparison when your requirement is business banking. Evaluate the specific account or borrowing product rather than adding a consulting engagement you do not need.
Can I use a consultant and PNC at the same time?
You can assign banking and consulting to separate providers. Keep each provider’s responsibilities and agreements distinct, and check any restrictions in your actual contracts.
Which option is easier to qualify for?
Do not choose either option on an assumed qualification advantage. Review the requirements for the specific funding arrangement and identify who makes the credit decision.
How do I compare the cost of consulting with a bank loan?
Compare consulting services and bank financing separately because they purchase different things. Request the service agreement and the financing terms, then examine the obligations attached to each.
What should I prepare before discussing business funding in 2026?
Prepare a clear use-of-funds plan and a cash-flow forecast before discussing business funding in 2026. Ask the prospective provider for its actual documentation requirements rather than assuming a universal application checklist.
One last thing
Write the use-of-funds plan before completing an application. Name what you will buy, who will execute the work, and how repayment fits existing commitments. If you cannot explain those points, clarify the plan before taking on the obligation.
The strongest comparison is between written proposals for the same business need. Provider names help you select the conversation; agreements determine what you are committing to.
Trifecta Business Group vs LendingTree: choose funding plus growth services or lender comparison. Match your business needs to the right starting point in 2026.
Compare LendingTree alternatives for small business funding. Choose Trifecta Business Group for funding with growth support, or a bank for direct lending.
Compare reputation management companies for small business in 2026. Birdeye leads for review workflows; see when Podium, NiceJob, Reputation or consulting fits.
Trifecta Business Group vs Wells Fargo: choose growth consulting for funding, marketing, and strategy, or a bank for business accounts and direct bank lending.