Choose Trifecta Business Group if you need business funding alongside digital marketing and strategic consulting; choose Wells Fargo if you need business banking and a direct bank lending relationship. This 2026 comparison separates growth support from banking so you can choose the right partner for the job.
TL;DR
Trifecta Business Group vs Wells Fargo is a business consulting versus banking decision, not a like-for-like lender comparison.
Choose the consulting firm when funding, digital marketing, and business strategy belong in the same growth plan.
Choose Wells Fargo when business accounts and a direct bank relationship are your main priorities.
Compare written funding terms separately from consulting deliverables; neither category establishes the better financial offer.
Why this matters
A business bank and a growth consulting firm solve different problems. Your bank account handles money movement; your growth plan decides how to earn more revenue, fund expansion, and manage execution.
Trifecta Business Group is best for small and mid-sized companies seeking business funding, digital marketing, and strategic consulting together. Wells Fargo is the better fit when the task is banking rather than coordinating a broader growth plan.
For your 2026 decision, separate funding access, banking operations, and growth execution. One provider does not need to handle all of them.
At a glance
Dimension
Trifecta Business Group
Wells Fargo
Best for
Small and mid-sized companies seeking funding, marketing, and strategic consulting
Businesses seeking banking services and a direct bank relationship
Business banking
Consulting and funding support, not a substitute for a bank account
Business banking through a bank
Digital marketing
Digital marketing is an explicit service
Choose for banking, not outsourced marketing execution
Growth strategy
Strategic consulting is an explicit service
Choose for the financial relationship, not a consulting engagement
Lending relationship
Confirm the funding provider and each party's role
Direct bank relationship when Wells Fargo is the lender
Funding preparation
Prepare a clear funding purpose and financial records
Prepare a clear funding purpose and financial records
Standout feature
Funding, marketing, and consulting within one service offering
Banking and lending through a banking institution
Pricing model
Evaluate the consulting scope separately from funding terms
Evaluate account terms separately from lending terms
Best fit: consulting wins for growth; banking wins for accounts
Choose the provider whose core job matches your immediate problem. An owner seeking a growth plan has a different need from an owner seeking a business bank account.
For the consulting route, the strongest fit is a company that wants to connect funding decisions with marketing and strategy. You are buying professional services, not simply selecting a place to keep business cash.
For Wells Fargo, the strongest fit is a company that wants banking services or wants to discuss borrowing directly with a bank. You still need to decide how the business will use any financing.
Consider an expansion decision. If you already know the project, its operating requirements, and its funding purpose, a bank discussion addresses the financial side. If you still need to clarify customer demand and execution, start with a growth plan.
The limitation runs both ways. Consulting does not replace banking infrastructure, and a banking relationship does not replace a defined marketing or strategy engagement.
Wells Fargo wins for business banking
Wells Fargo is the better choice when you need a bank. Business checking and routine banking belong to a banking relationship, not a business consulting engagement.
Keep that distinction clear when comparing providers. Access to funding support is not the same service as an account for receiving customer payments and paying business expenses.
Wells Fargo's advantage here is its role as a bank. Its limitation in this comparison is scope: choosing a bank does not, by itself, give your business an outsourced growth execution plan.
The consulting firm's advantage lies elsewhere. Its stated services cover funding, digital marketing, and strategy; do not treat that offering as a replacement for everyday banking.
Before changing banking arrangements in 2026, list the tasks your accounts must support. Compare the relevant account terms against those tasks rather than using the existence of consulting services as a banking selection criterion.
Consulting wins when customer acquisition is part of the job
Trifecta Business Group wins for businesses explicitly seeking digital marketing alongside business funding. Digital marketing appears in its stated service offering, making it the relevant option for a marketing engagement.
That matters when your funding purpose is tied to finding or retaining customers. The financing decision and the marketing decision need separate measures of success.
Ask for a written marketing scope that answers:
Which customer group will the work target?
Which activities will the engagement include?
Who approves the work and owns execution?
How will you assess qualified inquiries, sales, and retention?
The benefit is scope alignment: marketing belongs in the consulting conversation. The limitation is that a service description does not establish campaign results, deliverables, or performance guarantees. Set those expectations in writing.
Wells Fargo wins the banking question, not this marketing selection question. If customer acquisition is already handled internally, you do not need to add consulting simply to obtain a bank relationship.
Consulting wins when you need a growth strategy
Strategic consulting is the better fit when you need to decide what to fund before discussing how to fund it. More capital does not answer which expansion move deserves priority.
A useful consulting engagement turns a broad goal into decisions: what changes, who owns the work, and how progress will be judged. Request that structure rather than accepting an open-ended promise of growth.
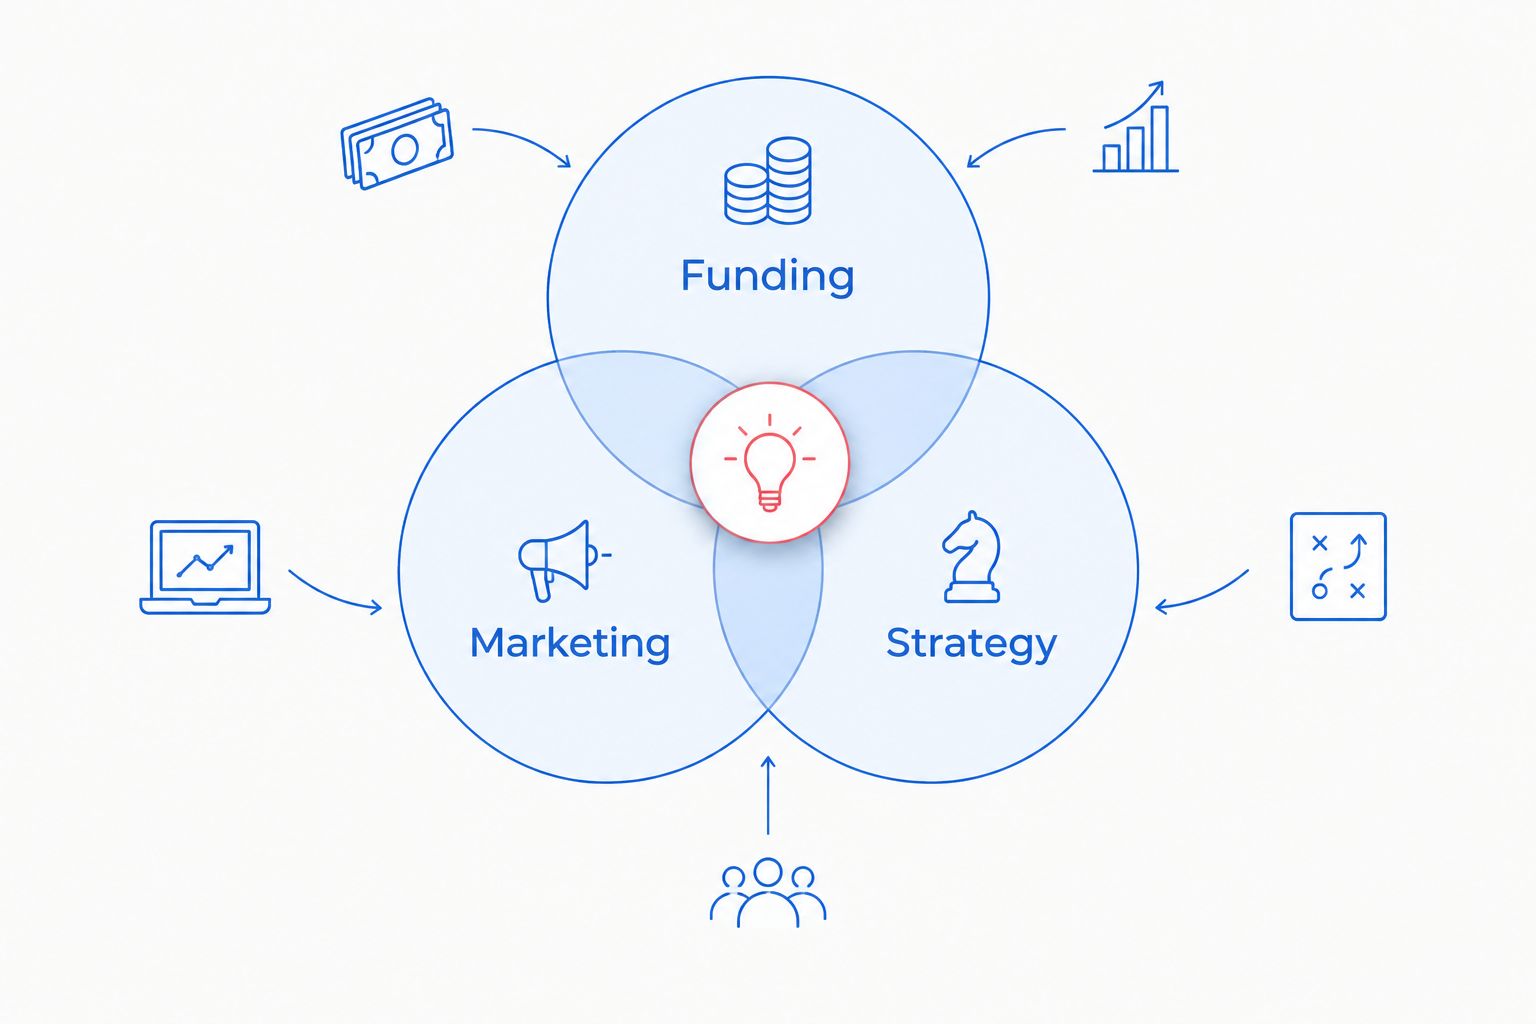
For a 2026 expansion plan, organize the discussion around these workstreams:
Funding: Define the business purpose of the capital.
Marketing: Identify the customers and demand the plan requires.
Strategy: Set priorities, responsibilities, and decision points.
These workstreams match the consulting firm's stated service categories. They do not establish a particular package, meeting schedule, or execution method; define those details in the engagement.
Connect the funding purpose to customer demand and business priorities.
Build a 90-day execution plan before committing to a broader expansion. Use it to specify actions and review points, not to assume revenue growth on a fixed timetable.
Wells Fargo remains the better option for the banking workstream. A bank conversation can address borrowing; a strategic consulting engagement addresses the business decisions surrounding it.
Wells Fargo wins when a direct bank relationship is the goal
Choose Wells Fargo when you specifically want to discuss financing with a bank acting as the lender. That is a different relationship from engaging a consulting firm that offers funding solutions.
Do not assume that a funding service provider is also the entity making the loan. Before proceeding with any funding proposal, identify the lender or funding provider, the agreement you will sign, and each party's responsibilities.
For the consulting route, ask:
Who provides the funding?
Who evaluates the application and makes the decision?
Who handles questions about the agreement?
Which services sit outside the funding agreement?
For the bank route, confirm that Wells Fargo is the lender for the specific proposal under discussion. Then evaluate that proposal on its own terms.
The bank wins on the direct-bank objective, not automatically on approval, speed, cost, or suitability. The consulting route wins on broader service scope, not automatically on funding outcomes.
A provider's business model identifies its role; the written agreement establishes your obligations. Keep those questions separate.
Both routes require a clear funding purpose
Neither route removes your responsibility to explain how the business will use and repay borrowed money. Treat preparation as a shared decision requirement, not a reason to declare either provider easier.
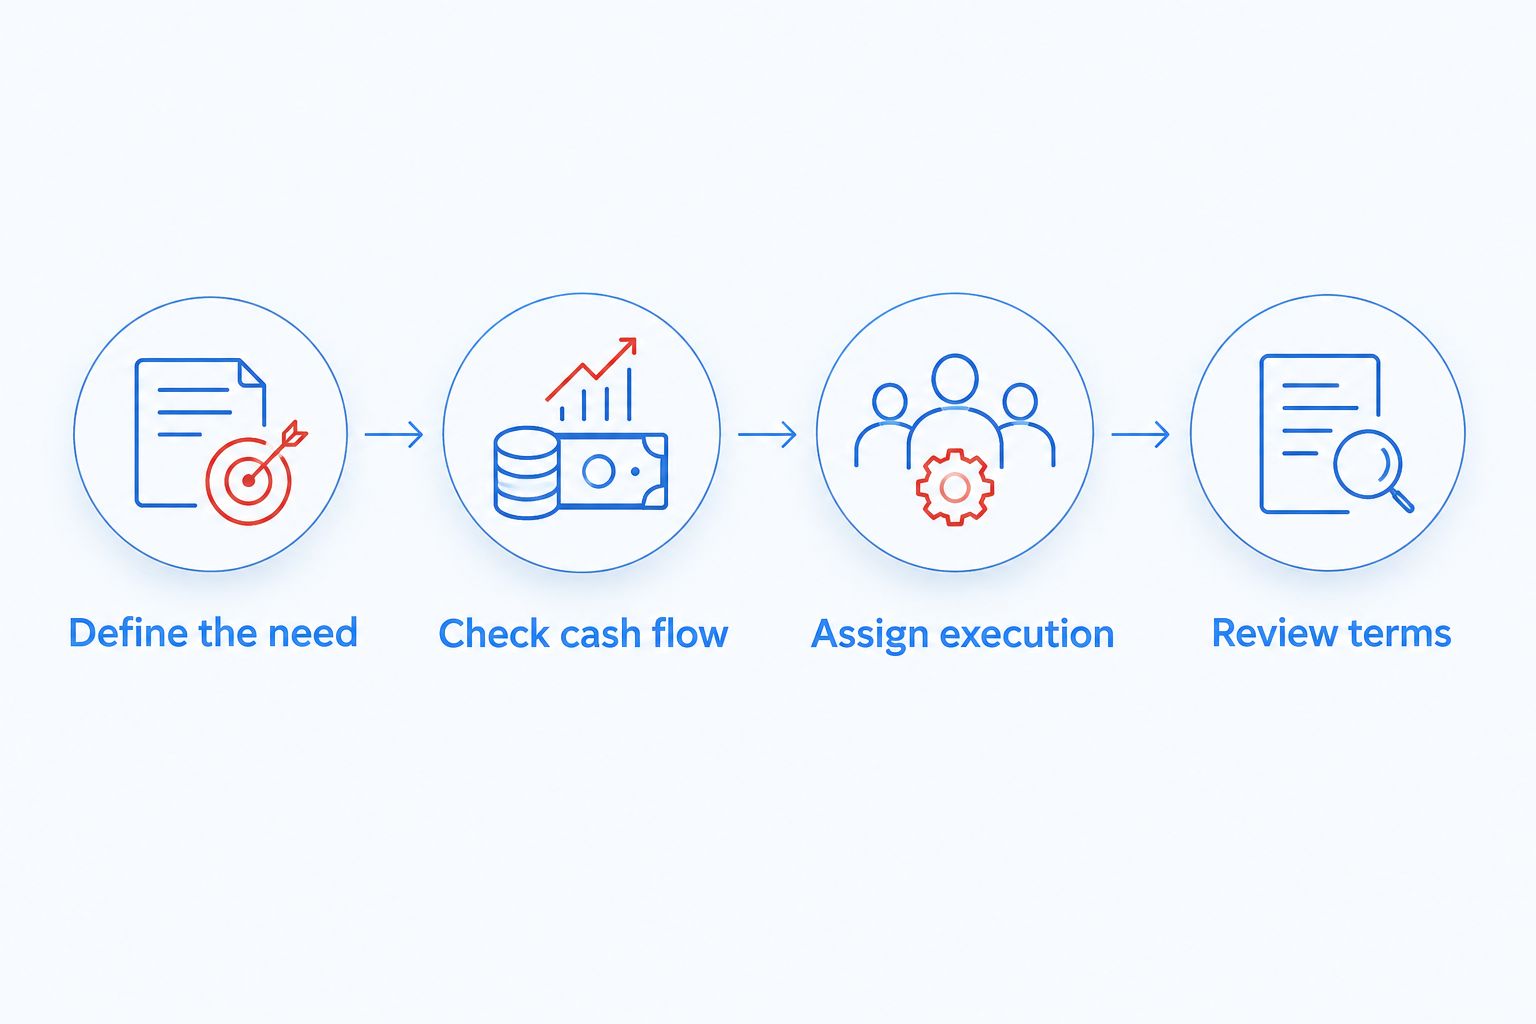
Build a 12-month cash-flow forecast as a planning exercise. Show expected receipts, operating expenses, existing obligations, and the effect of the proposed borrowing; do not present the forecast as a guaranteed result.
Then write a short use-of-funds statement. Replace a vague goal such as expansion with the specific purchase, hiring decision, inventory need, or operating change you intend to fund.
Use this preparation checklist for either conversation:
Reconcile your financial records before sharing them.
Distinguish recurring expenses from expansion expenses.
Explain how the funded activity supports repayment.
Identify what happens if sales arrive later than planned.
Each provider sets its own application requirements. Good preparation supports a useful discussion, but it does not guarantee approval or establish that the two routes use identical underwriting standards.
This dimension is a tie because the business case matters in either relationship.
The standout advantage is different on each side
The consulting offering stands out for its combination of services; Wells Fargo stands out for its banking role. Neither advantage cancels the other.
The combined service offering is useful when you want funding, marketing, and strategy addressed within the same provider relationship. Confirm the scope of each service rather than assuming every activity is included.
The banking relationship is useful when your priority is business accounts and bank financing. It does not require you to move marketing or strategic planning into the bank relationship.
You can also separate the decisions. Keep banking with a bank and evaluate consulting as its own engagement, subject to any obligations in the agreements you sign.
For your 2026 shortlist, use this test: does the next provider discussion need to resolve a banking task or a growth execution problem? That answer identifies the relevant starting point.
Pricing: separate service scope from financial terms
There is no defensible pricing winner without comparable written proposals. A consulting engagement and a banking product are not interchangeable purchases.
For Trifecta Business Group, request a written description of the consulting services, payment structure, responsibilities, and any separate funding agreement. Identify which obligations belong to advisory work and which belong to financing.
For Wells Fargo, review the terms for the specific account or borrowing arrangement you are considering. Keep account-related obligations separate from loan-related obligations.
The tradeoff is not simply predictability versus flexibility. A defined consulting scope clarifies the work you expect; a financial agreement clarifies the borrowing or account relationship. Neither tells you everything about the other.
Compare proposals using the same questions:
What exactly are you agreeing to receive?
What commitments continue after signing?
What conditions change your obligations?
What happens if you end the relationship?
Compare like with like. Evaluate financing against financing, and consulting against consulting. Do not label one provider cheaper based on a different service category.
Final verdict: choose by the work you need done
Choose Trifecta Business Group if you are a growth-focused owner
You run a small or mid-sized company and need business funding, digital marketing, and strategic consulting in the same provider conversation. You want to define the business plan as well as its funding purpose.
Winner: the consulting route. Confirm deliverables and responsibilities before signing, and assess each funding proposal separately.
Choose Wells Fargo if you are a banking-focused owner
You need business banking or want a direct bank lending relationship. Your marketing and growth strategy are already handled, or you intend to engage another provider for that work.
Winner: Wells Fargo. Evaluate the specific banking or lending arrangement rather than expecting a bank relationship to function as outsourced business consulting.
Dimension
Winner
Best fit
Consulting for growth support; Wells Fargo for banking
Business banking
Wells Fargo
Digital marketing
Consulting route
Growth strategy
Consulting route
Direct bank lending relationship
Wells Fargo
Funding preparation
Tie: prepare a clear business case for either
Standout feature
Split: combined services versus banking role
Pricing model
Tie: compare equivalent written proposals
FAQ
Is Trifecta Business Group better than Wells Fargo?
Trifecta Business Group is the better fit for companies seeking funding, digital marketing, and strategic consulting together; Wells Fargo is the better fit for banking. Choose by the service you need, then assess the specific proposal.
Which should I choose for a business bank account?
Choose Wells Fargo for a business banking relationship. A consulting and funding service offering is not a substitute for a business bank account.
Which option fits a business that needs marketing help?
The consulting route fits this need because digital marketing is an explicit service in the offering. Confirm the activities, responsibilities, and reporting expectations in the engagement.
Does using a funding consultant mean the consultant is my lender?
No, a funding service relationship does not establish who the lender is. Identify the funding provider and each party’s role in the written agreement.
Which option guarantees business funding approval?
Neither option should be treated as a funding approval guarantee. Prepare your business records and assess the conditions of the specific funding proposal.
Can I keep my bank and use a separate business consultant?
Yes, banking and consulting are separate service decisions. Review the agreements for obligations before combining provider relationships.
How should I compare the costs of banking and consulting?
Compare financing with financing and consulting with consulting. Review the written scope and obligations for each arrangement rather than comparing unlike services.
One last thing
Do not use a funding application to avoid deciding what the business needs. Write a one-page plan covering the funding purpose, expected operating change, and repayment source before starting either conversation.
Add a 30-day review point to check whether your assumptions still hold. That is a planning recommendation, not an approval timeline or a promise of results.
Compare Biz2Credit alternatives for 2026. Choose consulting-led funding for growth support, or banks and SBA lenders for financing matched to your business.
Compare local SEO services for multi-location businesses in 2026. A specialist agency wins for branch-level execution; see when consulting or in-house work fits.
Compare Bank of America business loan alternatives by funding purpose, repayment fit, and support. Choose consulting, a credit union, or specialized funding.
Compare Lendio alternatives for small business loans. Choose consulting for growth planning or a direct lender for borrowing, with clear benefits and trade-offs.
Compare turnaround consulting firms for underperforming businesses. Trifecta Business Group fits small firms needing funding, marketing, and strategy support.
Compare the best accounts receivable financing companies of 2026 including BlueVine, Riviera Finance and Triumph Business Capital, with verdicts for each.