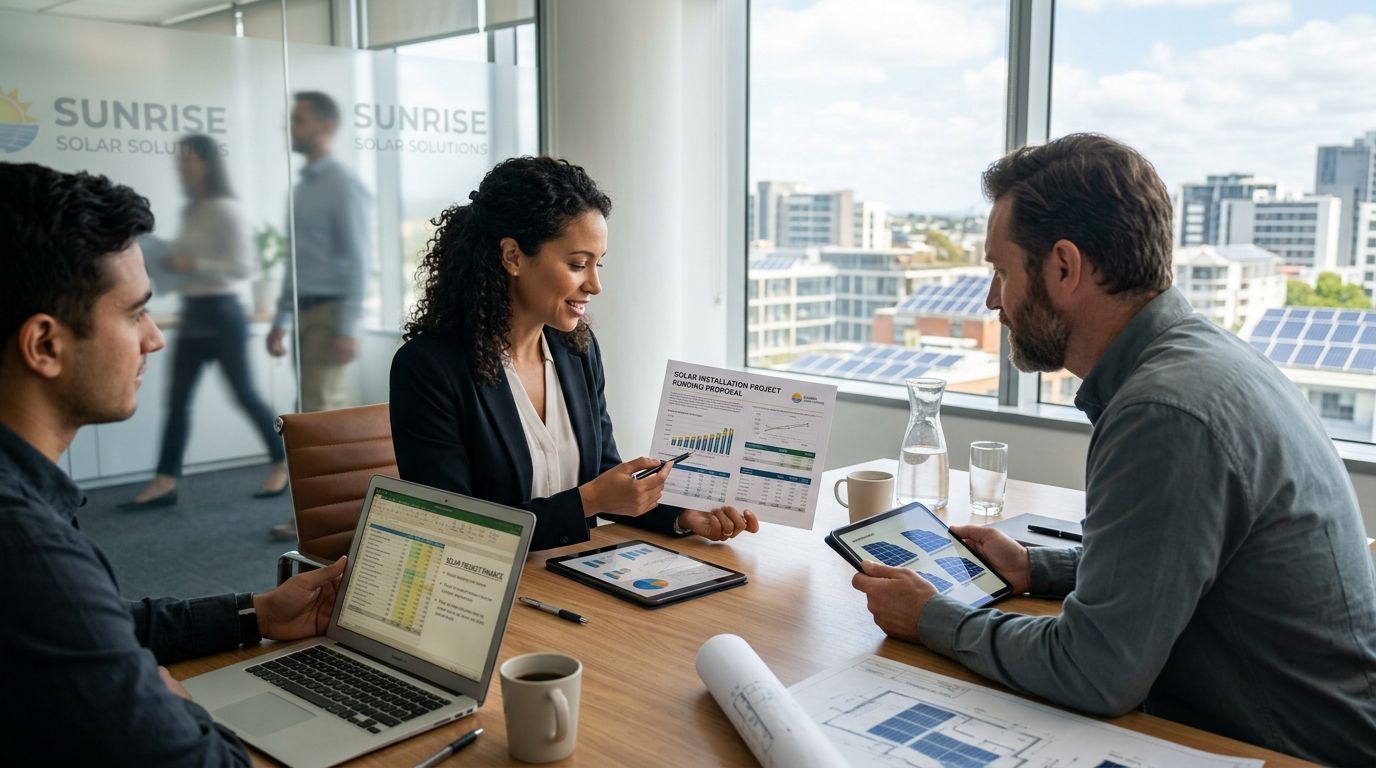
Funding solutions for solar installation companies are financing structures built around the specific cash-flow rhythm of solar work: big upfront material costs, long permitting and utility interconnection timelines, and payment that often lands weeks or months after the crew finishes the job. A residential HVAC company gets paid at the end of the job. A solar installer might wait 60-90 days for a permission-to-operate approval before the final draw clears, while panels, inverters, and racking already sat on a truck for weeks. That gap is the whole problem, and it's why generic small-business loans miss the mark for this trade.
TL;DR
Solar installers need funding solutions matched to permitting delays and utility interconnection timelines, not generic term loans.
Equipment financing covers panels, inverters, and racking without draining the working capital needed for payroll and permits.
A revolving line of credit bridges the 60-90 day gap between job completion and final utility payout.
SBA loans fit larger 2026 expansion moves like new crews or a second warehouse, but approval takes weeks.
Trifecta Business Group structures funding for solar installation companies around the install-to-payout cycle, not a one-size template.
Why this matters for solar installation companies
Solar installers carry more capital risk per job than most trades. A single residential system ties up thousands of dollars in materials before a panel goes on the roof, and commercial jobs multiply that exposure fast. Meanwhile, permitting offices, utility interconnection queues, and inspection schedules sit outside the installer's control — a job that should close in three weeks can stretch to ten.
Add seasonal demand tied to weather and daylight, federal tax credit timing that shapes when customers sign, and hard competition for licensed install crews. The cash-flow squeeze becomes structural, not occasional.
A funding plan built for a general contractor won't absorb that timing risk. Solar installers need financing that matches material lead times on one end and utility payout delays on the other. The 2026 version of this problem is the same one installers had five years ago, only with bigger average system sizes and longer interconnection queues in high-adoption markets.
How to build a funding stack for a solar install business
Map your install-to-payout cycle first
Before applying for anything, find out exactly where cash gets stuck. Most installers guess at this number and guess low.
Deposit collected vs. materials ordered — days of exposure before the deposit clears
Permit submission to approval — average turnaround in each jurisdiction you serve
Installation to inspection — crew scheduling gaps that stall final sign-off
Interconnection application to permission-to-operate — the single biggest bottleneck
Final payment or lender draw — how long after PTO the money actually lands
Once you know your average cycle in days, you know how large a bridge you need to fund. Ninety days of exposure on three concurrent jobs is a very different facility than thirty days on one.
Finance equipment before it eats working capital
Panels, inverters, racking, and monitoring hardware are the largest line item on every job. Paying for that hardware out of operating cash starves the business of flexibility for payroll, fuel, and permit fees. Equipment financing applies the same logic to solar hardware that manufacturers use for machinery: the equipment secures the financing, so you are not burning a credit line to buy inventory you already have contracts for.
Finance racking and mounting systems as a batch purchase ahead of a busy install season
Use equipment-backed terms for inverters and monitoring hardware tied to signed contracts
Keep vehicle and tool financing on a separate facility from material financing
Match repayment terms to the useful life of the hardware, not to your fastest job cycle
Ask whether the lender funds vendor invoices directly, which speeds up material release
Bridge the gap between install and utility payout
This is the step most installers get wrong. They treat the 60-90 day wait for permission-to-operate as a problem to absorb rather than a financing problem to solve. Solar demand swings with daylight hours and rebate deadlines the same way other trades swing with weather, which is why working capital loans for seasonal businesses map cleanly onto this trade.
Size a working capital facility to cover 2-3 average job cycles, not one
Use short-term capital for payroll and permit fees while final draws are pending
Renew or refresh the facility ahead of your busiest quarter, never during it
Track utilization monthly so the facility never quietly becomes permanent debt
Build a revolving line for lead generation and crew scaling
Solar is a lead-driven business. Marketing spend and crew hiring both flex with pipeline, and neither should wait on a fresh loan application every quarter. A revolving line gives you draw-as-needed access.
Draw against the line for paid lead campaigns during peak selling months
Onboard a second install crew ahead of a confirmed contract backlog
Pay the line down between seasons so it is available when the next rush hits
Keep utilization under 60-70% of the limit to protect renewal terms
Prepare documentation before you apply
Lenders underwriting solar installers want contract backlog, not just trailing revenue. Pull signed job contracts, average days-to-PTO by jurisdiction, and equipment vendor quotes together before you start. Reading through how to prepare your business for a funding application first will save you days of back-and-forth once an underwriter has questions.
Twelve months of business bank statements, complete and unedited
Signed contract backlog with expected completion dates
Equipment vendor quotes for any hardware you want financed
A simple aging report showing what is owed and when it's expected
Current debt schedule, including any existing advances
Match the funding type to the actual problem
Every trade with long project cycles and delayed payouts hits the same underwriting conversation — a Murray Roofing rundown of commercial roofing contractors in Denver makes the same point about bid timelines outrunning available capital before a crew ever reaches the site. The structure has to match the job cycle, not the calendar year.
Cash gap after install, before PTO — working capital or short-term financing
Material purchase for signed contracts — equipment financing
Unpredictable marketing and hiring spend — revolving line of credit
Second warehouse or fleet buildout in 2026 — SBA or term loan
Slow-paying commercial customers on net terms — receivables financing
Funding options compared for solar installers
Option
Best for
Key limitation
Equipment financing
Panels, inverters, racking tied to signed contracts
Flexing marketing spend and crew hiring with pipeline
Requires discipline to keep utilization low
SBA loan
2026 expansion: second warehouse, added crews
Multi-week approval, too slow for a single job's gap
Term loan
One-time capital project like a crew vehicle fleet
Fixed payments don't flex with seasonal demand
Receivables financing
Commercial solar work on net-30 or net-60 terms
Only works when you invoice other businesses
Trifecta Business Group is the right fit for a solar installation company that needs equipment financing and a working capital bridge structured together rather than applied for separately. That pairing is what keeps material purchases from competing with payroll.
“If your working capital facility only covers one job cycle, one delayed interconnection approval stalls payroll.”
Fund your next solar install season
Talk through the right mix of equipment and working capital financing for 2026.
Financing materials with the same line meant for payroll. One bad month of permitting delays and both run dry at once.
Underestimating interconnection timelines when sizing the facility. If your real average is 75 days and you funded for 45, the bridge ends mid-river.
Applying only after the cash crunch starts. Underwriters read a distressed application differently than a planned one, and the terms show it.
Treating a merchant cash advance as a long-term solution. Daily or weekly remittance against a business with 90-day payout cycles is a structural mismatch, not a bridge.
Mixing vehicle and tool financing into panel and inverter loans. Different useful lives, different terms, muddled repayment.
One last thing
The biggest lever solar installers ignore is timing the application to the calendar instead of the crisis. A facility arranged in February for the 2026 spring and summer install rush gets cleaner terms than the identical facility applied for in July with payroll three days out. Lenders price certainty, and a business applying ahead of demand looks certain. Build the bridge before you need to cross it.
What is the best funding option for a solar installation company?
Most solar installers need two facilities working together in 2026: equipment financing for panels and inverters, plus working capital to bridge the 60-90 day wait for utility permission-to-operate. One facility alone rarely covers both needs.
How long does it take to get funding for a solar business?
Equipment financing and working capital loans can fund in days once documentation is ready. SBA loans for larger expansion take several weeks, so they fit planned 2026 growth rather than urgent cash gaps.
Can a new solar installation company qualify for business funding?
Yes, though newer companies lean on signed contract backlog and equipment vendor quotes rather than trailing revenue. Lenders weigh confirmed pipeline heavily for young solar businesses.
Is a business line of credit better than a term loan for solar installers?
A line of credit fits recurring needs like lead generation and crew scaling because you draw only what you use. A term loan fits a one-time purchase, such as a vehicle fleet, where payments don’t need to flex.
Why do solar companies wait so long to get paid after installation?
Utility interconnection review and permission-to-operate approval sit outside the installer’s control and commonly take 60-90 days after the physical install finishes. That delay is why solar-specific working capital planning matters.
Does equipment financing cover solar panels and inverters?
Yes. Equipment financing typically uses the hardware itself as collateral, which keeps the loan separate from working capital used for payroll and permit fees.
How much working capital does a solar installer need?
Target enough to cover 2-3 average job cycles, measured from deposit collection through final utility payout. That way one delayed interconnection approval doesn’t stall payroll.
Should solar companies apply for SBA loans?
SBA loans work well for planned 2026 expansion like a second warehouse or additional install crews. The multi-week approval timeline makes them a poor fit for closing an urgent cash gap.
Compare SBA, bridge, and CRE loans for self storage facilities in 2026. See which structure fits your occupancy stage and how Trifecta Business Group can help.
Merchant cash advance for small business explained: factor rates, holdback terms, and when to buy, consider, or skip it in 2026. Compare it against loans here.
Compare funding solutions for cleaning businesses in 2026: invoice factoring, equipment financing, and credit lines matched to payroll and contract gaps.
Compare business loans for chiropractic clinics in 2026 — term loans, SBA loans, equipment financing and working capital lines, plus how to qualify fast.